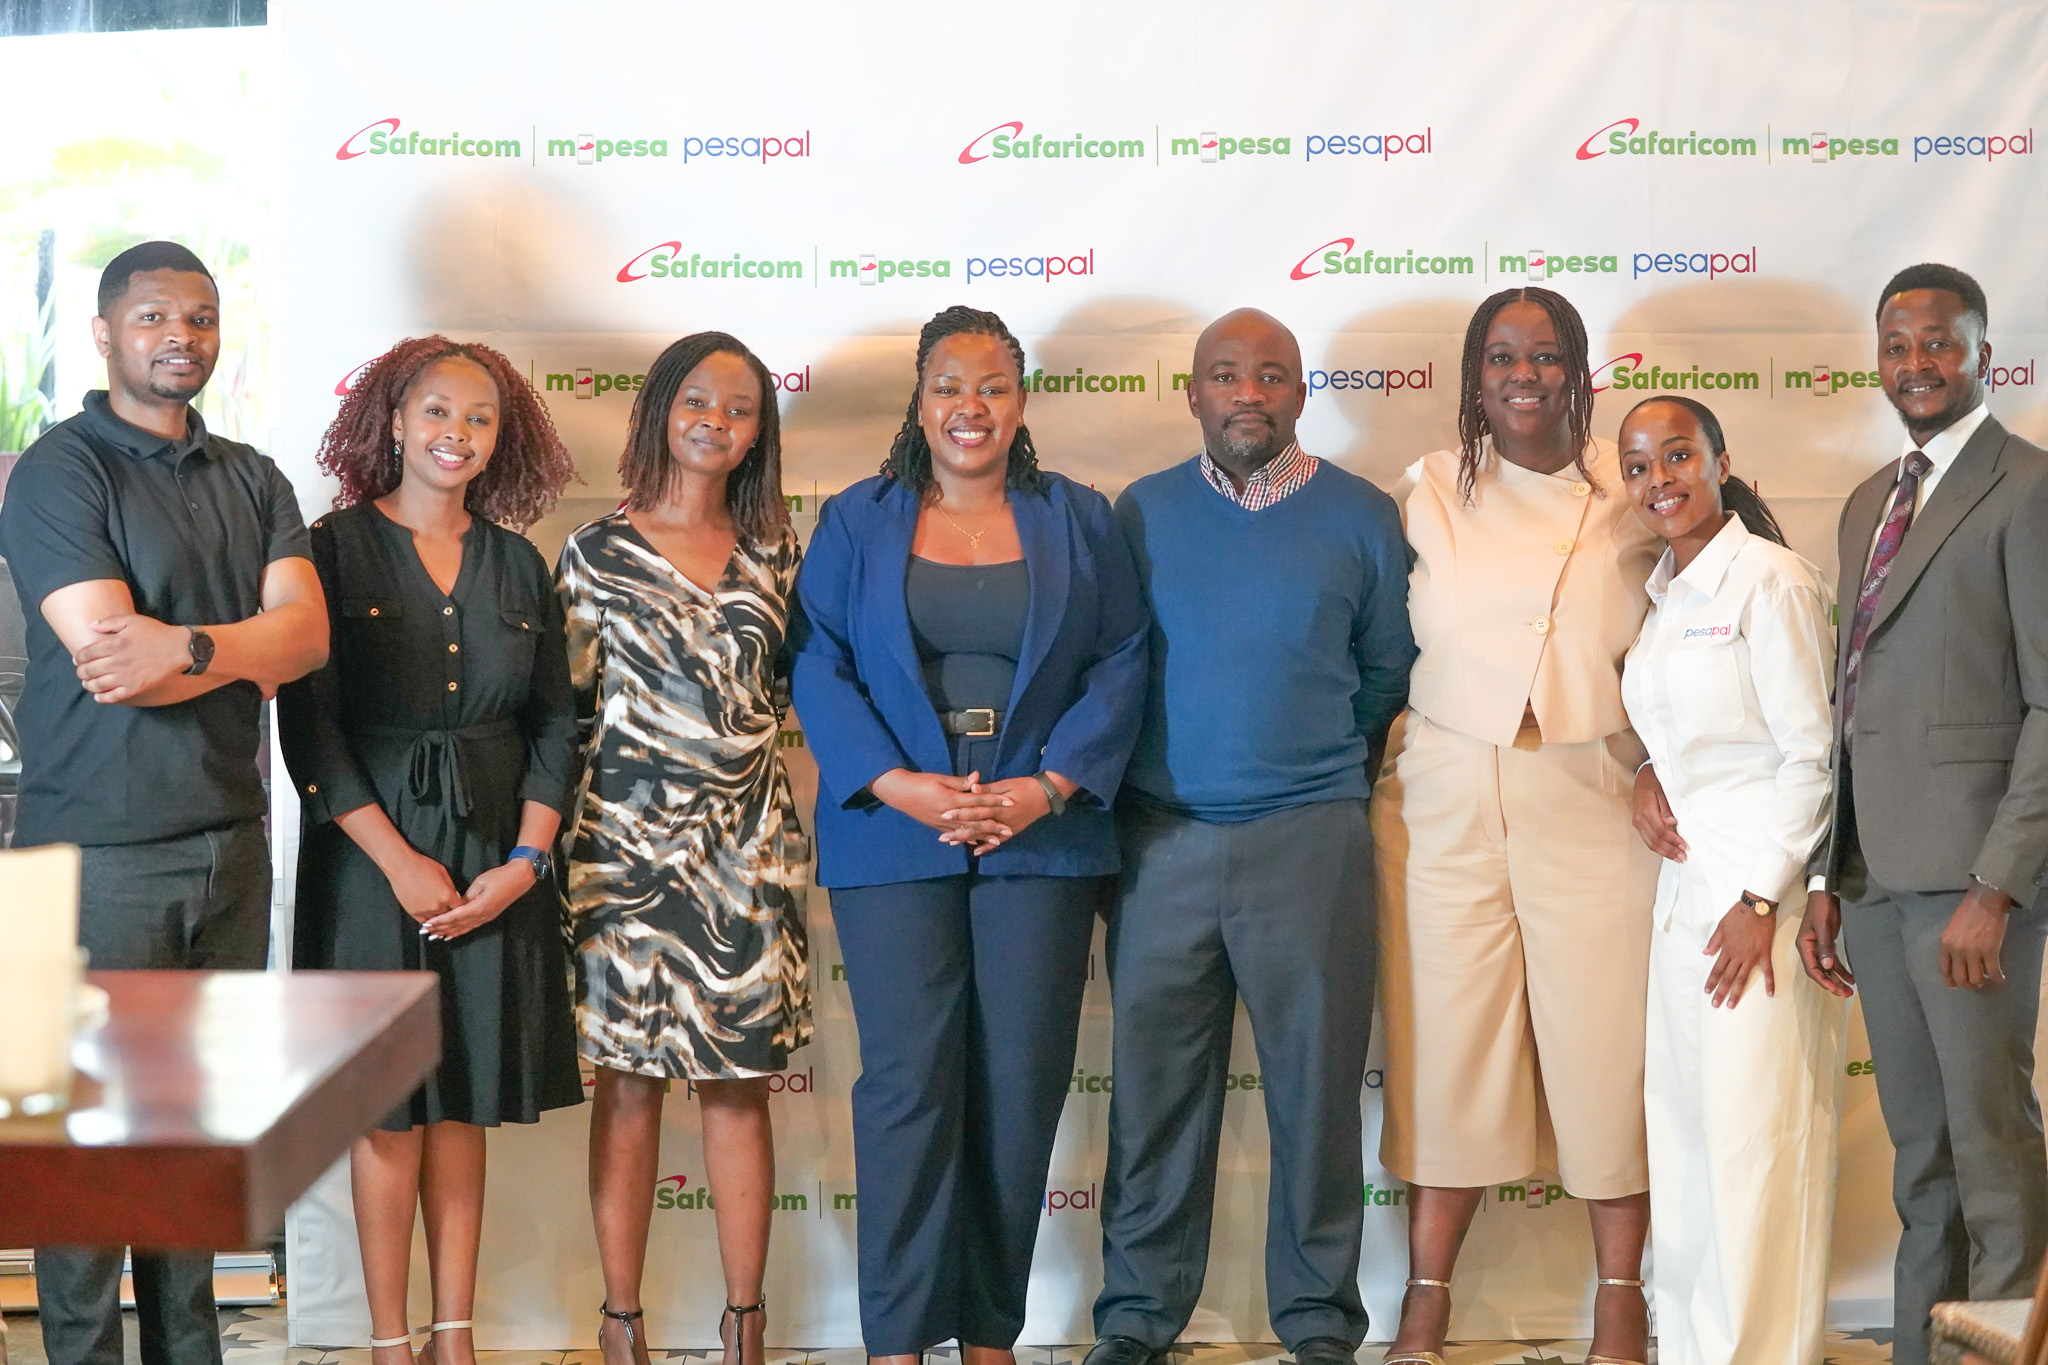

Safaricom and Pesapal are expanding M-PESA payment options with Dynamic Scan-to-Pay, Tap-to-Pay and AI Pay, giving Kenyan customers more ways to pay at participating businesses.
Paying for goods in Kenya is becoming less dependent on manually entering Till numbers and payment amounts.
Safaricom and Pesapal have announced a collaboration that brings new M-PESA payment experiences to participating businesses, including Dynamic Scan-to-Pay and Tap-to-Pay through Pesapal point-of-sale devices.
Safaricom is also rolling out AI Pay through its My OneApp, allowing customers to use their phone camera to identify payment information from receipts where the required details can be recognised.
The developments are part of a broader shift in Kenya’s digital payments market, where mobile money, QR codes, contactless technology and artificial intelligence are increasingly being combined into everyday transactions.
What is changing with M-PESA payments?
Traditionally, a customer paying through M-PESA at a business may need to identify the merchant’s Till or PayBill number, enter the amount and then confirm the transaction.
The new payment options are designed to reduce some of those manual steps.
With Dynamic Scan-to-Pay, a QR code displayed on a participating Pesapal POS device can contain the relevant merchant and transaction information.
A customer scans the code using a compatible payment experience, reviews the details and completes the transaction.
Safaricom’s current My OneApp listing also identifies Scan to Pay QR, AI Pay and NFC as available payment capabilities.
How Dynamic Scan-to-Pay works
Dynamic Scan-to-Pay is designed around the checkout process.
For example, imagine a customer buying household items worth KSh2,500 from a participating shop.
Instead of manually entering the merchant’s payment details and typing KSh2,500, the merchant’s Pesapal POS can display a QR code containing the relevant transaction information.
The customer scans the code and checks:
- The merchant details
- The payment amount
- The transaction information
The customer can then authorise the M-PESA payment.
The main advantage is reducing the amount of information a customer has to enter manually.
This can also reduce opportunities for typing mistakes, although customers should still check the payment information before confirming any transaction.
Tap-to-Pay brings NFC to the checkout
The second major development is Tap-to-Pay.
Instead of scanning a QR code, customers with compatible NFC-enabled smartphones can tap their device against a supported Pesapal POS terminal.
NFC, or Near Field Communication, is the technology that allows compatible devices to exchange information over a very short distance.
For Kenyan consumers, this means another payment option alongside QR codes, cards and traditional M-PESA transactions.
Pesapal already provides businesses with payment solutions for online and physical locations and operates POS services for merchants in Kenya.
What does a customer need for Tap-to-Pay?
The customer needs a compatible smartphone with NFC functionality and access to a supported payment experience.
The merchant also needs compatible payment equipment.
Therefore, Tap-to-Pay should not be interpreted as meaning that every M-PESA merchant in Kenya will immediately accept NFC payments.
Availability will depend on the merchant’s equipment and the services enabled on that device.
AI Pay could reduce manual payment entry
Safaricom is also pushing artificial intelligence further into the payment process through AI Pay.
The feature is available through My OneApp and is designed to identify payment information from receipts.
According to Safaricom, a customer can scan a receipt, including a printed or handwritten receipt, and AI Pay can identify information such as a Till or PayBill number and payment amount where the relevant information is available.
That could be particularly useful when a customer receives an invoice or receipt containing payment instructions.
Instead of manually reading the number and entering it into a payment screen, the customer can use the camera-based process to populate the information.
However, AI-generated or automatically recognised information should still be checked before payment is authorised.
An incorrect Till number or amount could result in a payment going to the wrong destination.
Why this matters for Kenyan businesses
Kenya already has one of Africa’s most established mobile-money ecosystems.
Your recent TechDrivers analysis of Kenya’s mobile-money market found that mobile-money subscriptions reached 54 million by June 2026, while M-PESA accounted for 88.8% of subscriptions.
That large existing user base gives merchants a reason to keep improving the way customers pay.
For a busy supermarket, restaurant, pharmacy, electronics shop or other retailer, saving even a few seconds per transaction can become significant when multiplied across hundreds of customers.
For example, if a merchant processes 300 digital payments in a day and a new checkout method saves an average of 10 seconds per transaction, that represents roughly 50 minutes of cumulative customer interaction time across those transactions.
The actual time saved will vary by customer, device, network and payment method, but the example illustrates why checkout efficiency matters at scale.
Safaricom targets 500,000 Scan-to-Pay outlets
Safaricom says Scan-to-Pay is currently available at more than 60,000 merchant outlets.
The company has set a target of reaching 500,000 outlets within the next year.
That would represent an increase of more than eight times from the current stated footprint.
The expansion would also move QR-based M-PESA payments beyond individual early adopters and into a much larger portion of everyday retail.
For Kenyan consumers, the availability of the technology will ultimately depend on whether individual businesses adopt compatible payment equipment.
M-PESA is becoming more than a money-transfer service
The development is another example of how M-PESA has evolved beyond its original role as a mobile-money transfer service.
Today, consumers use mobile money for:
- Sending money
- Buying goods
- Paying bills
- Paying businesses
- Accessing financial services
- Online purchases
- Receiving payments
The broader Kenyan financial ecosystem is also becoming increasingly digital.
As we reported in Kenyan Banks Turn to Digital Banking as Interest Rates Fall, banks are increasingly investing in digital banking, payments, customer data and automation as financial services become more technology-driven.
The Safaricom-Pesapal rollout fits into the same wider transformation.
AI is moving closer to everyday transactions
AI Pay is particularly interesting because it shows how artificial intelligence is moving from chatbots and content generation into routine financial tasks.
Instead of asking an AI system to produce text or answer a question, the technology is being used to interpret information contained in a receipt and help prepare a payment.
That is consistent with a wider shift we have covered at TechDrivers.
In AI Will Not Become Your Employee. It Will Change How Work Is Managed, we examined how AI is increasingly being connected to systems where everyday work actually happens.
Payments are another example of that transition.
The technology is becoming useful not simply because it can generate information, but because it can help reduce repetitive steps in a real-world process.
What this could look like at a Kenyan shop
Consider a small electronics retailer in Nairobi.
A customer buys a smartphone accessory for KSh3,500.
Traditional digital payment
The customer may:
- Ask for the merchant’s Till number.
- Open the M-PESA payment interface.
- Enter the Till number.
- Enter KSh3,500.
- Check the details.
- Authorise the transaction.
Dynamic Scan-to-Pay
The process could instead involve:
- The merchant enters the transaction on the POS.
- The POS displays a dynamic QR code.
- The customer scans the code.
- The merchant and amount are populated.
- The customer verifies the details.
- The customer authorises the payment.
Tap-to-Pay
Where supported:
- The merchant enters the transaction.
- The customer taps an NFC-enabled phone on the POS.
- The customer reviews the transaction.
- The customer authorises the payment.
The exact user experience can vary depending on the device, software and payment configuration.
What customers should watch out for
Faster payments do not eliminate the need for caution.
Customers should continue checking the merchant name and amount before authorising a transaction.
For QR payments, do not assume that every QR code displayed in a public place is legitimate.
For AI Pay, automatically recognised information should also be reviewed before payment.
Customers should never disclose their M-PESA PIN to a merchant, stranger or anyone claiming to need it to complete a payment.
A faster payment process is useful only if the transaction is going to the intended recipient for the correct amount.
What this means for the future of payments in Kenya
The combination of mobile money, QR payments, NFC and AI points toward a checkout experience where customers increasingly interact with payment technology rather than manually entering payment instructions.
For businesses, the benefit is potentially faster checkout and better integration between physical sales and digital payment records.
For consumers, the attraction is convenience.
But the success of the rollout will depend on adoption.
A payment technology can only become useful at scale if enough merchants have compatible equipment and enough customers have compatible phones and payment applications.
Safaricom’s stated target of 500,000 Scan-to-Pay outlets will therefore be an important number to watch over the coming year.
Frequently Asked Questions
What is Safaricom Dynamic Scan-to-Pay?
Dynamic Scan-to-Pay allows customers to scan a QR code displayed on a participating merchant’s Pesapal POS device. The relevant merchant and payment information can then be populated for the customer to review before completing the transaction.
What is M-PESA Tap-to-Pay?
Tap-to-Pay is a contactless payment option that uses NFC-enabled smartphones with compatible payment equipment.
What is AI Pay?
AI Pay is a Safaricom feature designed to identify payment information from receipts and populate relevant details such as a Till or PayBill number and amount where the information can be recognised.
Does every smartphone support NFC?
No. NFC availability depends on the smartphone model and configuration. Customers need a compatible device to use NFC-based Tap-to-Pay.
Can I use Dynamic Scan-to-Pay at every M-PESA merchant?
No. The feature depends on participating merchants and compatible payment equipment.
Is AI Pay available through the M-PESA app?
Safaricom’s current My OneApp listing identifies AI Pay alongside Scan to Pay QR and NFC payment capabilities.
Is Pesapal regulated in Kenya?
Pesapal states that Pesapal Limited is regulated by the Central Bank of Kenya.
Conclusion
Safaricom and Pesapal’s latest payment collaboration shows how Kenya’s digital-payment ecosystem is moving toward simpler and more automated transactions.
Dynamic Scan-to-Pay aims to reduce manual entry at the checkout, Tap-to-Pay introduces another contactless option for compatible devices, while AI Pay uses image recognition to help identify payment information from receipts.
The bigger story is not simply the introduction of three new payment features.
It is the continued transformation of the Kenyan mobile phone into a payment interface.
For customers, however, convenience should still go hand in hand with verification: check the merchant, check the amount and confirm the transaction before authorising it.
