
Kenya’s banking industry is entering a period where making money from banking is increasingly about more than lending money.
As interest rates have fallen, banks are placing greater emphasis on digital banking, payments, mobile transactions, data, automation, insurance, wealth management and other financial services.
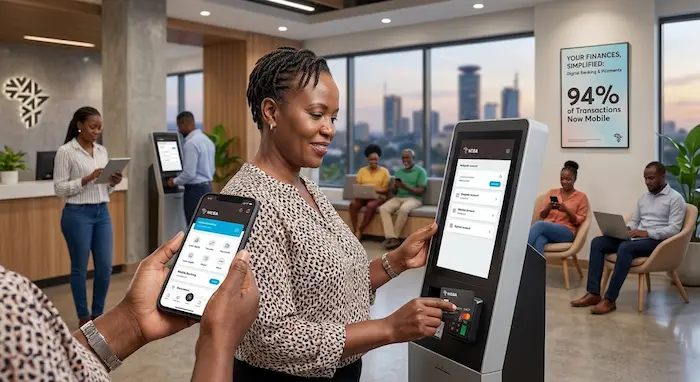
The change is particularly visible in how customers interact with banks. Visiting a branch is no longer the only way to transfer money, apply for a loan, pay a bill or manage an account. Increasingly, those activities happen through mobile apps, USSD platforms, cards, online banking and integrated payment systems.
The shift matters because digital transactions can allow banks to serve more customers at lower operating costs while creating additional opportunities to generate revenue from financial activity.
Kenya’s interest rates have been falling
The Central Bank of Kenya (CBK) has significantly reduced its policy rate since early 2025.
The Central Bank Rate stood at 8.75% as of August 11, 2026, compared with 10.75% in February 2025. CBK’s August 2026 data also put the average commercial-bank lending rate at 14.34%.
Lower rates can make borrowing more affordable and encourage businesses and households to seek credit.
CBK reported that private-sector credit growth reached 10.6% in June 2026, up from 5.9% in December 2025. The central bank attributed the improvement partly to increased demand for credit as lending rates declined.
For banks, however, lower lending rates can also change the economics of traditional interest-based banking.
This makes other sources of income and greater operational efficiency increasingly important.
Why digital banking matters to Kenyan banks
Digital banking is not simply about replacing bank branches with mobile applications.
It changes how banks acquire customers, process transactions, assess borrowers and deliver financial products.
A digital customer can potentially:
- Open or manage an account remotely
- Transfer money through a mobile app
- Pay bills electronically
- Make card or online purchases
- Apply for a digital loan
- Receive transaction notifications
- Purchase insurance products
- Access investment or wealth-management services
- Interact with a bank without visiting a branch
Every additional digital interaction also creates data that can help a financial institution understand customer behaviour, subject to applicable privacy and data-protection requirements.
That information can help banks develop more targeted products and improve risk assessment.
Payments are becoming a bigger part of the banking experience
Kenya’s mobile-money ecosystem has already made digital payments part of everyday life.
Banks increasingly operate within that broader digital financial ecosystem rather than relying exclusively on traditional branch banking.
Customers expect instant transfers, digital payments, card services and mobile access.
For banks, payment activity can create revenue through transaction-related services while also strengthening relationships with customers.
The more frequently a customer uses a bank’s digital platform, the more opportunities the institution has to provide other financial products.
This is one reason banks are investing heavily in mobile applications, payment infrastructure, APIs and business banking platforms.
Digital lending is changing how banks reach borrowers
Digital lending is another important part of the transformation.
Instead of requiring every customer to begin the borrowing process at a branch, banks can use digital platforms to automate parts of loan applications and approvals.
NCBA provides one example.
The bank reported that its digital loans disbursed reached KSh819 billion in H1 2026, representing a 26.9% year-on-year increase. It also said mobile banking accounted for 94% of transaction volumes during the period.
Those figures illustrate how digital channels can become central to a bank’s operations rather than functioning merely as an additional service.
Digital lending can also make it possible to serve customers seeking relatively small amounts of credit that might not justify a traditional branch-based process.
However, digital lending does not eliminate credit risk. Banks still need effective credit assessment, responsible lending practices, fraud controls and systems for dealing with defaults.
Banks are investing in technology and AI
The transformation is also moving beyond mobile apps.
Banks are investing in artificial intelligence, cybersecurity, automation, cloud infrastructure, customer relationship systems and data analytics.
NCBA said it invested KSh2.4 billion in technology infrastructure in H1 2026, including investments intended to accelerate AI adoption, strengthen cyber resilience and support core operations.
AI can potentially be used in areas such as:
- Customer-service automation
- Fraud detection
- Credit assessment
- Document processing
- Personalised financial products
- Internal operations
- Cybersecurity monitoring
The technology also introduces new risks.
Banks must protect customer information, maintain reliable systems and ensure automated decisions are appropriately governed.
For customers, this means the quality of a bank’s technology infrastructure can increasingly be as important as the size of its branch network.
Data is becoming a strategic banking asset
A modern bank handles enormous amounts of information.
Every payment, transfer, loan application and account interaction can generate data.
When properly governed, this information can help banks understand:
- How customers use financial services
- Which products customers need
- How customers manage cash flow
- Where fraud risks may exist
- Which digital services are working
- How businesses use banking services
Data can therefore become part of the competitive advantage of a financial institution.
But there is an important distinction between using data responsibly and simply collecting as much information as possible.
Kenyan banks operate within a regulatory environment that includes data-protection requirements. Customers should therefore pay attention to how financial institutions explain the collection and use of their personal information.
Branches are not disappearing
The rise of digital banking does not necessarily mean Kenyan banks will eliminate physical branches.
Some customers still need face-to-face services, particularly for complex financial products, business banking, large transactions or issues that cannot easily be resolved through an app.
Branches can also remain important for customer acquisition and relationship management.
The more likely change is that branches become part of an omnichannel banking model.
A customer might begin a loan application online, communicate with a bank through a call centre and complete a complicated transaction at a branch.
The digital and physical channels therefore increasingly work together.
Banks are looking beyond traditional lending
Lower interest rates are also encouraging banks to look at other parts of the financial-services market.
These can include:
Payments
Banks can generate income from payment and transaction services while increasing customer engagement.
Insurance
Banks can distribute insurance products through bancassurance operations, allowing customers to access additional financial products from the same institution.
Wealth management
Customers with savings and investments can be offered products beyond conventional deposit accounts.
Asset finance
Banks can finance vehicles, equipment and other assets while developing digital platforms around those products.
SME banking
Small and medium-sized businesses require payments, credit, cash-management and other financial services.
Investment banking
Corporate customers may require advisory, capital-markets and investment services.
This diversification means banks are increasingly trying to become broader financial platforms rather than simply places where people deposit money and take loans.
What this means for Kenyan customers
For consumers, the shift toward digital banking has several practical consequences.
1. Banking can become more convenient
Customers can complete many transactions without travelling to a branch.
2. Services can become faster
Automated systems can process certain transactions and applications much faster than manual processes.
3. Competition can increase
Banks competing through mobile applications, payment services and digital products may have greater incentives to improve customer experience.
4. Cybersecurity becomes more important
More digital banking also means more opportunities for phishing, account takeovers, SIM-related fraud and other cyber threats.
Customers should use strong passwords, enable available security features and avoid sharing PINs, passwords or one-time authentication codes.
5. Data privacy matters more
The more financial activity moves online, the more important it becomes for customers to understand how their information is collected and protected.
Kenya’s banks are becoming technology companies too
It would be an exaggeration to say banks are abandoning traditional banking.
Loans and deposits remain fundamental to the industry.
However, the technology layer around those products is becoming increasingly important.
A bank today needs reliable payment systems, mobile applications, cybersecurity infrastructure, data platforms, automated processes and digital customer-support channels.
That creates a different competitive environment from traditional banking.
The institution with the largest branch network does not automatically have the most convenient digital experience.
The opportunity for Kenyan fintech companies
The transformation also creates opportunities beyond established banks.
Kenyan fintech companies can provide technologies for:
- Digital payments
- Identity verification
- Credit scoring
- Fraud detection
- Financial management
- Business payments
- Digital insurance
- Investment platforms
- Banking infrastructure
Banks can build these systems internally, partner with technology companies or combine both approaches.
This creates a growing intersection between Kenya’s banking industry and its technology ecosystem.
The risks behind the digital shift
Digital banking also comes with challenges.
Cybersecurity: More online activity creates a larger attack surface.
Fraud: Criminals can exploit social engineering, stolen credentials and fraudulent transactions.
System outages: When customers depend heavily on mobile and online banking, downtime can become disruptive.
Data protection: Banks must handle sensitive financial information responsibly.
Digital exclusion: Customers without smartphones, reliable internet access or digital skills can still face barriers.
Algorithmic risk: Automated credit or fraud systems can produce errors if poorly designed or monitored.
The digital transformation therefore needs to be accompanied by investment in security, reliability, customer education and responsible technology governance.
What happens if interest rates rise again?
Banks cannot assume that interest rates will always remain low.
Monetary policy can change as inflation, economic growth and other conditions change.
That makes diversification useful beyond the current interest-rate environment.
A bank that has strong payment services, digital channels, wealth management, insurance and efficient technology infrastructure may have more ways to generate income across different economic conditions.
The current environment is therefore not simply about responding to lower rates.
It is also about preparing for how banking will work in the future.
What Kenyan customers should watch
As banks become more digital, customers should look beyond the interest rate when comparing financial services.
Consider:
- Loan interest and other charges
- Transaction fees
- Mobile and online banking functionality
- Customer support
- Security features
- App reliability
- Data-privacy practices
- Availability of financial products
- Withdrawal and transfer costs
- Terms and conditions
A low advertised interest rate does not automatically mean a financial product is the cheapest option.
Customers should consider the total cost of using a financial service.
Related TechDrivers stories
The growth of digital banking connects with several other technology trends covered by TechDrivers.
For example, our coverage of how Kenyan consumers use mobile data helps explain why mobile-first financial services need to work efficiently even for customers relying on limited or expensive data.
Our coverage of M-Pesa and phone theft also highlights why securing a smartphone has become increasingly important as more financial activity moves onto mobile devices.
The wider shift toward AI and automation is covered in our article on how AI could change the way work is managed, while our coverage of the AI digital teammate looks at how organisations are beginning to incorporate AI into everyday workflows.
Together, these trends show that Kenya’s digital economy is increasingly built around smartphones, connectivity, financial technology, data and automation.
Frequently Asked Questions
Why are Kenyan banks investing more in digital banking?
Digital banking can reduce the cost of serving customers, improve convenience and create opportunities around payments, lending and other financial services. Banks are also responding to customers’ growing preference for mobile and online services.
Are Kenyan banks making less money because interest rates are falling?
Not necessarily. Lower rates can put pressure on lending margins, but banks can benefit from stronger credit demand, lower funding costs and growth in other financial services. Individual banks can experience different results depending on their business models.
What is driving digital banking in Kenya?
Smartphone adoption, mobile money, internet connectivity, fintech innovation, customer demand for convenience and banks’ investments in technology are among the major factors driving digital banking.
Is digital banking safer than visiting a bank branch?
Digital banking can be secure when properly designed and used, but it introduces risks such as phishing, malware, account takeover and social engineering. Customers should use official banking applications and never share passwords, PINs or authentication codes.
Will bank branches disappear in Kenya?
There is no indication that branches are becoming irrelevant overnight. Physical branches can continue to serve customers who need complex or face-to-face services, while routine transactions increasingly move to digital channels.
How does data help banks?
Data can help banks understand customer behaviour, detect suspicious activity, assess credit risk and develop financial products. Banks must still comply with applicable data-protection and privacy requirements.
What does lower interest rates mean for borrowers?
Lower lending rates can reduce the cost of borrowing, although the actual rate offered to an individual customer depends on the bank, loan product, borrower risk and other pricing factors.
Conclusion
Kenya’s banking industry is moving toward a model in which digital transactions, payments, data and technology sit alongside traditional lending and deposits.
The falling interest-rate environment has increased the importance of this transformation, but the shift is larger than interest rates alone.
Banks are investing in mobile platforms, digital lending, AI, cybersecurity, payments and other financial services because customers increasingly expect banking to be fast, convenient and available from their phones.
For Kenyan consumers and businesses, the result could be more convenient financial services and greater product choice.
But it also means customers need to become more aware of digital security, transaction costs and how financial institutions handle their personal data.
The future of Kenyan banking is therefore unlikely to be purely about how much a bank lends.
It will increasingly be about how effectively it combines money, technology, data and customer relationships.
Editorial note: This article is an independent TechDrivers analysis based on publicly available information from the Central Bank of Kenya and published financial results. Figures cited for individual banks represent those institutions’ reported results and should not be interpreted as representing the entire Kenyan banking industry.
