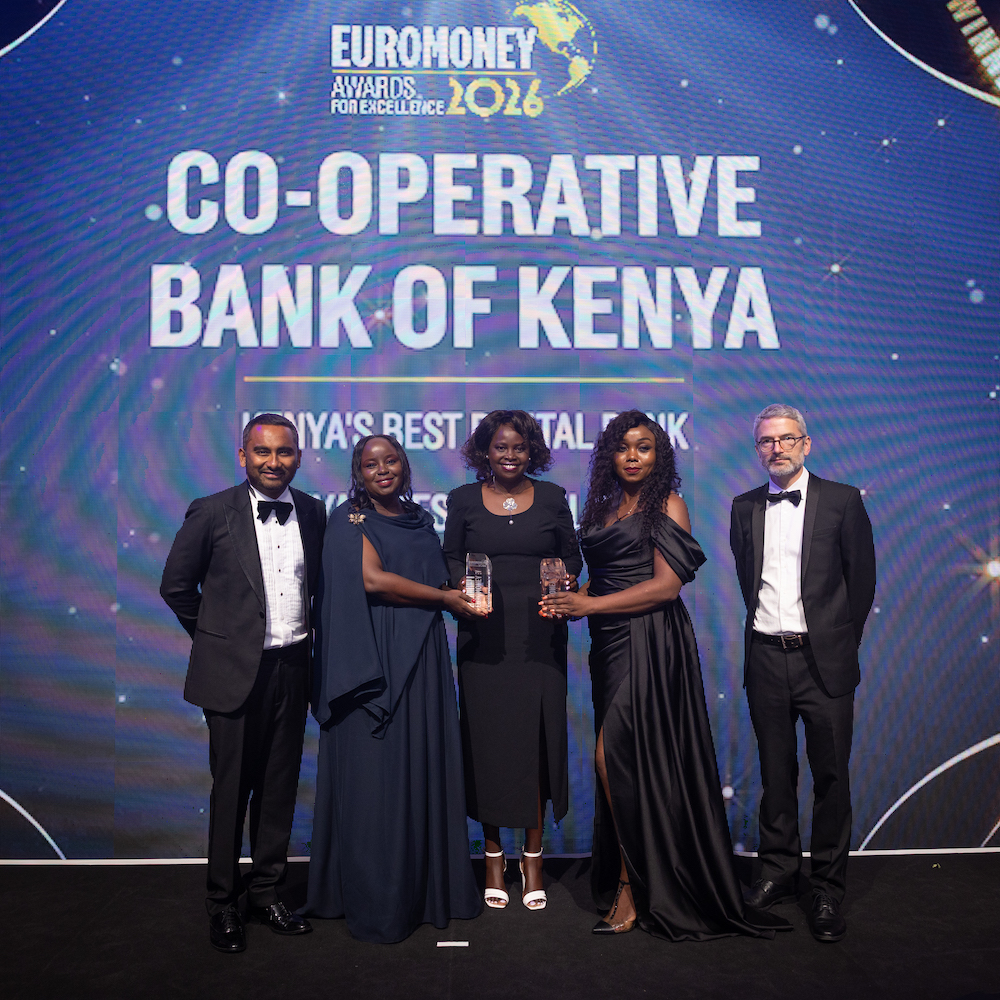

Co-operative Bank of Kenya has been named Kenya’s Best Retail Bank and Best Digital Bank in the Euromoney Awards for Excellence 2026, giving the bank two of the country’s notable banking recognitions this year.
The awards are significant because they come at a time when Kenyan banking is rapidly moving beyond traditional branch-based services. Customers increasingly expect to open accounts, transfer money, access credit, make payments and manage their finances through digital channels.
Euromoney’s assessment highlighted Co-op Bank’s investment in digital platforms, customer access, financial inclusion and its wider digital banking ecosystem. The bank says more than 90% of its transactions are now processed through digital and alternative channels.
But what does the recognition actually tell us about the future of banking in Kenya?
What Co-operative Bank Won
The 2026 Euromoney Awards for Excellence recognized Co-operative Bank in two Kenya-specific categories:
- Kenya’s Best Digital Bank
- Kenya’s Best Retail Bank
Euromoney’s Awards for Excellence program has operated for more than 30 years and evaluates financial institutions based on areas including performance, innovation and client impact. The 2026 awards ceremony was held on July 16, with results published the following day.
The recognition should therefore be viewed in the context of how banks are improving their services and using technology to change the customer experience.
Why Co-op Bank Was Recognized as Kenya’s Best Digital Bank
According to Euromoney, Co-op Bank has invested in a broad digital architecture covering mobile banking, USSD, online platforms, open banking and integrations with other systems.
One particularly notable figure is the bank’s more than 1,000 APIs, which allow its banking infrastructure to connect with internal systems, fintech companies, enterprise customers and third-party platforms.
This matters because modern digital banking is no longer simply about having a mobile application.
A bank’s digital infrastructure determines how easily different services can work together.
For example, a customer may interact with a bank through:
- A mobile application
- USSD
- Internet banking
- A payment platform
- A merchant service
- A digital lending product
- An external fintech service
The ability to connect these systems can make banking faster and more convenient.
More Than 90% of Transactions Are Digital
One of the clearest indicators of Co-op Bank’s digital shift is transaction volume.
Euromoney reports that more than 92% of the bank’s transactions are processed through digital channels. Co-op Bank’s own financial disclosures similarly report that more than 90% of customer transactions are handled through alternative delivery channels.
This does not mean branches have become irrelevant.
Instead, it shows that many routine banking activities are increasingly moving away from physical branches.
Customers can perform many everyday transactions through digital and alternative channels without visiting a branch.
That creates potential benefits for both customers and banks.
For customers, digital services can provide greater convenience.
For banks, shifting routine transactions to digital channels can improve operational efficiency and allow branches and staff to focus on services that require direct interaction.
The Co-op Bank App Is Becoming More Important
The bank has also invested in its mobile application.
Co-op Bank says its new app has been integrated with investment services, while Euromoney notes that the application offers more than 100 features.
This reflects a broader change in financial technology.
A modern banking application is increasingly expected to provide more than a simple account balance.
Customers may want to:
- Check account balances
- Transfer money
- Pay bills
- Make payments
- Access financial products
- Manage investments
- Apply for credit
- Receive notifications
- Access customer support
The more services that can be securely provided through one platform, the less customers may need to rely on physical branches for routine activities.
Digital Lending Is Another Major Part of the Transformation
Digital banking isn’t only about payments.
Access to credit is another area where technology is changing how customers interact with financial institutions.
Euromoney reported that Co-op Bank’s unsecured digital lending proposition had disbursed KSh54.2 billion to nearly 1.8 million retail and micro, small and medium-sized enterprise customers by the third quarter of 2025.
The bank’s wider disclosures also show substantial use of its E-Credit platform, with cumulative disbursements exceeding KSh500 billion since launch.
Digital lending can make the application process more convenient, but customers should still pay close attention to:
- Interest charges
- Fees
- Repayment periods
- Penalties
- Eligibility requirements
- Total cost of borrowing
Convenience should not be confused with affordability.
Digital Banking Is Also Changing SME Payments
Small and medium-sized businesses are another important part of Co-op Bank’s digital strategy.
Euromoney highlighted several services aimed at businesses and merchants, including Co-op Till, ChapaPay and Pay by Link.
These types of digital payment tools can help businesses accept payments without relying entirely on traditional cash transactions.
For a small business, digital payment systems can potentially make it easier to:
- Receive customer payments
- Track transactions
- Reconcile sales
- Manage business finances
- Build a record of business activity
The availability of digital records can also become useful when businesses need better visibility into their cash flow.
Digital Banking Does Not Mean Branches Are Disappearing
One of the interesting aspects of Co-op Bank’s strategy is that digital expansion is happening alongside a physical banking network.
Euromoney reported that the bank had 221 branches across 43 counties in Kenya, while the bank’s own financial disclosures reported 222 branches across the wider group structure at the end of 2025.
This suggests that the future of banking is not necessarily about choosing between branches and digital platforms.
Instead, banks are increasingly building omnichannel banking, where customers can move between digital services, agents, ATMs, contact centres and branches depending on what they need.
A customer might use a mobile application for everyday transactions but still visit a branch for a complicated financial service.
What This Means for Kenyan Bank Customers
The most important question is not simply whether Co-op Bank won an award.
It is what the wider digital transformation means for customers.
1. More Banking Services Can Move Online
As banks invest in their digital infrastructure, more services can potentially be completed remotely.
This can reduce the need for customers to travel to branches for routine activities.
2. Banking Can Become More Convenient
Mobile and online platforms allow customers to access services outside traditional branch operating hours.
That is particularly useful for customers who work during the day or live far from a branch.
3. Digital Credit May Become More Accessible
Technology can make loan applications and disbursements faster.
However, easier access to credit also means customers need to make responsible borrowing decisions.
4. Businesses Can Get Better Digital Payment Options
Merchants increasingly have access to tools that can help them accept and manage digital payments.
This supports Kenya’s broader shift toward a digital economy.
5. Cybersecurity Becomes More Important
The more banking activities move online, the more important cybersecurity becomes.
Customers should protect:
- PINs
- Passwords
- One-time passwords
- Mobile devices
- Banking applications
- Recovery information
Banks can invest heavily in security, but customers also play an important role in protecting their accounts.
The Cybersecurity Challenge
Digital transformation creates opportunities, but it also introduces new risks.
Fraudsters can target customers through:
- Phishing messages
- Fake banking websites
- Social engineering
- SIM-related scams
- Fake customer-care accounts
- Malicious applications
- Fraudulent payment requests
Customers should never share their banking PIN, password or one-time authentication codes with another person.
They should also be cautious about clicking banking links received through unexpected messages.
A digital bank can provide sophisticated security infrastructure, but no system can completely eliminate the risk created by customers unknowingly giving criminals access to their credentials.
Why This Matters for Kenya’s Fintech Industry
Co-op Bank’s recognition also highlights the changing relationship between traditional banks and fintech companies.
Banks are increasingly building APIs, integrating external platforms and developing digital products rather than operating as isolated financial institutions.
This creates opportunities for:
- Fintech partnerships
- Digital payments
- Open banking
- SME technology
- Digital lending
- Financial-management tools
Euromoney specifically highlighted Co-op Bank’s ability to connect its systems with fintech partners, enterprise customers and third-party platforms.
That is an important development because Kenya already has one of Africa’s most active digital-finance ecosystems.
What the Award Does Not Mean
Winning Best Digital Bank does not mean every customer will have a perfect digital banking experience.
An award is recognition of performance against particular criteria; it is not a guarantee that every product, application or transaction will work perfectly at all times.
Customers should continue evaluating banks based on factors that matter to them, including:
- Availability of digital services
- Transaction costs
- Security
- Customer support
- Reliability
- Loan terms
- Accessibility
- Branch and agent availability
The right bank for one customer may not necessarily be the right bank for another.
What to Look for in a Modern Digital Bank
Co-op Bank’s recognition provides a useful opportunity to consider what customers should expect from digital banking in general.
A strong digital banking service should ideally provide:
Reliable Access
Customers should be able to access important services consistently.
Strong Security
Banks should use appropriate authentication and security measures to protect customer accounts.
Simple User Experience
Digital banking should make transactions easier rather than unnecessarily complicated.
Transparent Charges
Customers should be able to understand transaction fees and other costs before using a service.
Useful Financial Products
Digital platforms should provide practical services rather than simply moving existing paperwork onto a mobile application.
Human Support
Customers should have access to human assistance when an automated system cannot resolve a problem.
The Bigger Picture
Co-operative Bank’s two Euromoney awards reflect a broader transformation taking place across Kenya’s financial sector.
Banking is becoming increasingly digital, but the transformation is about more than replacing branches with mobile applications.
It involves rebuilding financial services around:
- Mobile technology
- APIs
- Digital payments
- Data
- Automation
- Digital lending
- Customer experience
- Financial inclusion
Co-op Bank’s reported 92% digital transaction share shows how quickly customer behaviour can change when digital services become convenient and widely accessible.
The next stage will likely be about making those services even more useful, secure and personalized.
TechDrivers Take
Co-operative Bank’s recognition as Kenya’s Best Digital Bank and Best Retail Bank in the 2026 Euromoney Awards for Excellence is significant, but the bigger story is the technology behind the recognition.
The bank’s investment in digital platforms, APIs, digital lending, mobile services and SME payment solutions demonstrates how traditional financial institutions are adapting to a market where customers increasingly expect banking to happen through their phones and other digital channels.
For Kenyan consumers and businesses, this competition can be positive.
As banks invest more heavily in technology, customers should benefit from greater choice, more convenient services and potentially better digital experiences.
But convenience should always be balanced with security.
The future of Kenyan banking is unlikely to be entirely digital or entirely physical. Instead, it will be connected banking, where mobile apps, digital payments, agents, ATMs, contact centres, branches and fintech platforms work together.
And for customers, the most important measure will ultimately not be the number of awards a bank wins.
It will be whether its technology makes banking safer, easier, more accessible and genuinely useful.
Frequently Asked Questions
What awards did Co-operative Bank win in 2026?
Co-operative Bank was named Kenya’s Best Digital Bank and Kenya’s Best Retail Bank in the Euromoney Awards for Excellence 2026.
Why did Co-operative Bank win Best Digital Bank?
Euromoney highlighted the bank’s investment in mobile, USSD, online banking, APIs, open banking, digital lending, SME payment services and customer-experience technology.
How much of Co-op Bank’s transactions are digital?
Euromoney reported that more than 92% of transactions are processed through digital channels. Co-op Bank’s own FY2025 disclosure similarly reported that more than 90% of customer transactions were processed through alternative delivery channels.
Does digital banking mean branches are no longer necessary?
No. Digital channels are increasingly handling routine transactions, but branches remain important for customers who need physical assistance or more complex services.
Is digital banking safe?
Digital banking can use strong security technologies, but customers must also protect their credentials and remain alert to phishing, fraud and social-engineering attacks.
Is Co-op Bank the best bank for everyone?
Not necessarily. An award recognizes performance against specific criteria. Customers should compare banks based on their own needs, including fees, digital services, security, customer support, accessibility and financial products.
