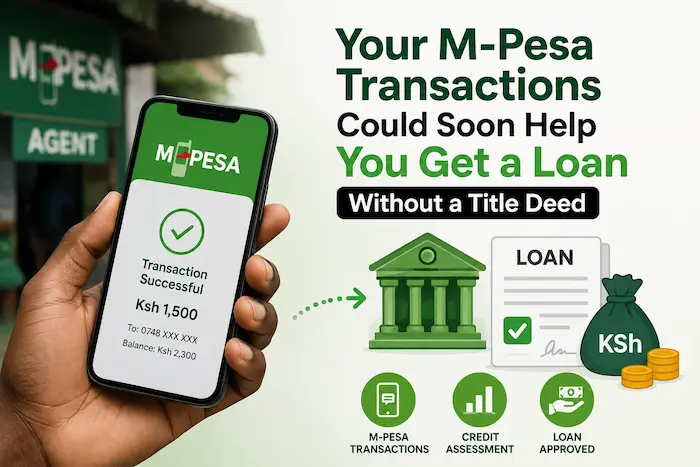

For years, getting a substantial loan from a traditional lender in Kenya has often meant proving that you have something valuable to secure it.
A title deed.
A vehicle logbook.
A payslip.
Bank statements.
A guarantor.
But that model is beginning to change.
Kenya’s rapidly growing digital economy has created another valuable asset: financial data.
Every time a business receives money through M-Pesa, pays a supplier, settles a bill or records a sale, it creates a digital trail. Lenders and fintech companies are increasingly exploring how these transaction patterns can be used to understand whether someone can repay a loan.
The idea is simple:
Your financial behaviour could become almost as important as the assets you own.
‘Data is the new collateral’
The idea gained fresh attention in Kenya in August 2026 after Spinmobile CEO Victor Kiplagat told a Nairobi forum of banking, microfinance, digital-lending and SACCO executives that “data is the new collateral.”
The argument is particularly relevant for small traders, boda boda operators, barbers and other informal businesses that may generate consistent income but lack traditional assets to pledge against a loan.
Instead of asking only, “What do you own?”, lenders can increasingly ask:
“What does your financial activity tell us about your ability to repay?”
That is where M-Pesa and other digital transaction platforms become important.
How M-Pesa data can help lenders assess borrowers
A lender doesn’t necessarily need to look at one transaction and decide whether someone deserves a loan.
Instead, technology can analyse patterns over time.
For example, an AI-powered credit scoring system could potentially examine:
- How frequently money enters an account
- The consistency of income
- Average transaction values
- Business sales patterns
- Supplier payments
- Seasonal changes in revenue
- Repayment behaviour
- Cash-flow stability
- Payment history
- The difference between personal and business transactions
The objective is to build a more complete picture of a borrower’s financial behaviour.
The Central Bank of Kenya has itself highlighted the use of alternative data in credit scoring as a way of expanding credit information and supporting access to finance for micro, small and medium-sized enterprises.
This is already happening—not just a future idea
The shift toward alternative credit scoring is already underway in Kenya.
In July 2026, Kenya News Agency reported on an AI-powered financing model from fintech company Avenews that uses transaction data to assess the creditworthiness of agribusinesses that may struggle to provide traditional collateral. The model uses AI and machine learning to analyse business information and support financing decisions.
KBC also reported that Avenews analyses information including M-Pesa statements, bank statements and other financial transaction histories to assess customers.
Other fintech platforms are taking a similar approach.
For example, Mwezi says its AI credit-scoring system can use M-Pesa history, bank information and other business data to generate a credit profile for SMEs.
This points to a broader transformation in Kenyan lending.
Why this could be a big deal for small businesses
Consider a small shop owner in Nairobi.
The business may generate KSh 10,000, KSh 20,000 or even KSh 50,000 in sales on good days, but the owner may not have a title deed.
Under a traditional lending model, the business could appear risky because there is little conventional collateral.
But transaction data could tell a different story.
A lender might see months of consistent sales, regular supplier payments and relatively predictable cash flow.
That information could help the lender determine that the business is more creditworthy than its lack of physical assets suggests.
This could be particularly important for Kenya’s micro and small enterprises, which often operate outside traditional financial structures.
The opportunity for ‘thin-file’ borrowers
Another important group is borrowers with limited formal credit histories.
Someone may have never taken a large bank loan but could still have years of digital financial activity.
Alternative-data models can potentially turn some of that activity into useful credit information.
The International Finance Corporation says alternative data—including mobile-money transactions, digital payments and business-platform records—is increasingly being explored to improve credit access for underserved borrowers.
That could help people who are financially active but poorly represented by traditional credit systems.
M-Pesa could become even more important in business lending
M-Pesa is particularly significant because of how deeply mobile money is integrated into Kenya’s economy.
A July 2026 TechCabal report noted that Safaricom is looking at how its extensive M-Pesa transaction data could support business finance, arguing that digital payment activity can provide insight into how businesses earn, spend and manage cash flow.
This could create a major shift.
Instead of a lender relying primarily on a balance sheet or physical collateral, the lender could potentially evaluate the real-time economic activity of a business.
For a small retailer, that might mean daily sales.
For an online seller, it could mean payment receipts.
For an agricultural business, it could mean seasonal transaction patterns.
For a boda boda operator, it could mean income patterns from digital platforms and payments.
AI is making the process faster
The other major piece of this transformation is artificial intelligence.
A human loan officer cannot manually analyse thousands of transactions for every applicant.
AI systems can.
Machine-learning models can process large amounts of information and identify patterns that may be difficult to spot manually.
That could make loan decisions faster while allowing lenders to evaluate borrowers who previously fell outside traditional scoring models.
But there is an important warning.
AI does not automatically make lending fair.
The quality of the data matters.
If the data is incomplete or biased, an algorithm can reproduce or even amplify those problems.
Researchers studying credit scoring in Nairobi have highlighted the complex technical and regulatory issues surrounding alternative data and algorithmic credit assessment.
What about your privacy?
This is where the conversation becomes more complicated.
Your M-Pesa transactions contain sensitive information about your financial life.
They can reveal where you spend money, how frequently you receive payments, who you transact with and how your income changes over time.
That means lenders cannot simply treat transaction data as a free-for-all.
Kenya already has regulations governing digital credit providers, including requirements around data protection and consumer protection. The CBK has also warned about the abuse of personal information by unregulated digital lenders.
The Central Bank has further recognised the importance of safeguards around the collection, storage and sharing of payments data.
So as alternative-data lending expands, trust and privacy will be just as important as the technology itself.
Could your M-Pesa history guarantee a loan?
No.
This is an important distinction.
Having a strong M-Pesa transaction history does not automatically mean a lender will approve your application.
Lenders will still consider risk.
They may assess income stability, existing debts, repayment history, business performance and other factors.
The major change is that transaction history could become one of the key pieces of evidence used to make that decision.
In other words:
Your M-Pesa history could strengthen your loan application, but it is not a guaranteed loan ticket.
What this could mean for Kenyans without collateral
If the model develops successfully, Kenya could see a significant change in how credit is distributed.
A small business owner may no longer need to own land simply to prove that they are financially reliable.
A young entrepreneur without years of banking history could potentially build a financial reputation through digital transactions.
A farmer could demonstrate business activity through transaction records.
A trader could demonstrate consistent cash flow without presenting a title deed.
This could make the financial system more responsive to the realities of Kenya’s digital economy.
But there are risks
The move toward data-driven lending also creates new challenges.
1. Privacy
Consumers need to know what data is being collected and how it is being used.
2. Algorithmic bias
If an AI system is trained on poor or biased data, deserving borrowers could still be rejected.
3. Data security
The more financial information lenders collect, the more attractive those databases become to cybercriminals.
4. Over-borrowing
Easier access to digital credit could encourage some consumers to take on more debt than they can comfortably repay.
5. Transparency
Borrowers should be able to understand, at least in meaningful terms, why an automated system considers them high- or low-risk.
These concerns mean Kenya’s next phase of digital lending will need strong consumer protection alongside technological innovation.
Kenya is moving from ‘assets’ to ‘activity’
The most interesting part of this transformation is philosophical.
Traditional lending asks:
What assets do you have?
Data-driven lending increasingly asks:
What does your economic activity tell us about you?
That is a major shift.
For millions of Kenyans operating small businesses without land, vehicles or formal financial statements, the second question could be much more relevant.
Kenya’s digital economy has already created an enormous financial footprint through mobile money.
The next stage could be turning that footprint into a new form of financial identity.
The bottom line
Your M-Pesa transactions are not literally becoming a title deed.
But they could increasingly become evidence of your ability to repay.
As banks, fintechs, SACCOs and digital lenders adopt AI and alternative-data credit scoring, financial behaviour could play a much larger role in determining who gets access to capital.
For Kenya’s millions of small businesses, that could be a significant development.
The future of lending may not be about what you own. It may increasingly be about what your financial data says you can afford.
