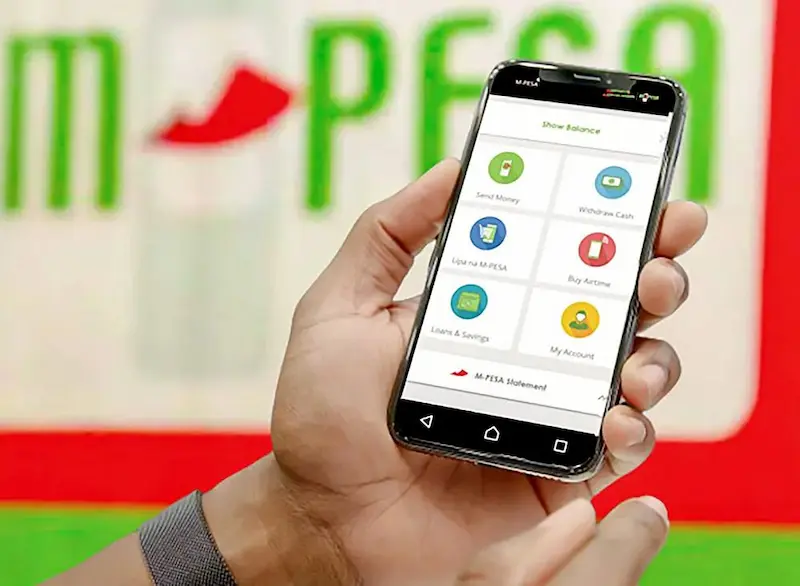

Kenyan M-PESA customers have a new investment option designed for people who want to grow their money without investing in products that conflict with Islamic financial principles.
Safaricom and GulfCap Investment Bank launched the Ziidi Shari’ah Money Market Fund on 6 October 2026, allowing eligible customers to start investing with KSh 100. Customers can access the fund through My OneApp or by dialling *334#, with subsequent contributions starting at KSh 10.
The launch expands the investment options available through mobile financial services in Kenya. But before investing, customers need to understand how the fund works, how returns are generated, what the advertised fees cover and why Shariah compliance does not eliminate investment risk.
Here is what Kenyan investors should know.
What is the Ziidi Shari’ah Money Market Fund?
The Ziidi Shari’ah Money Market Fund is an investment product launched by Safaricom in partnership with GulfCap Investment Bank, also known as GCIB.
It is designed for customers seeking investments that follow Shariah principles, which include avoiding interest-based transactions, known as riba, and excluding prohibited business activities.
According to GulfCap, the fund operates under the oversight of its Shariah Supervisory Board and is regulated by Kenya’s Capital Markets Authority (CMA). It operates independently from Safaricom’s conventional Ziidi Money Market Fund.
The distinction matters because the two products are not simply different names for the same investment. They are intended to follow different investment principles.
For Kenyan customers who have avoided conventional interest-bearing products for religious or ethical reasons, the new fund provides another route into formal investment services through a familiar mobile platform.
How much do you need to start investing?
One of the product’s main attractions is its relatively low entry point.
| Feature | Announced terms |
|---|---|
| Minimum initial investment | KSh 100 |
| Minimum subsequent top-up | KSh 10 |
| Access channels | My OneApp or *334# |
| Deposits into the fund | Advertised as free |
| Withdrawals to M-PESA | Advertised as free |
| Maximum fund investment | No stated maximum, subject to applicable M-PESA transaction limits |
| Fund manager and partner | GulfCap Investment Bank |
| Regulatory oversight | Capital Markets Authority |
These are the terms announced at launch. Customers should check the official product terms and on-screen disclosures before investing because product conditions may change.
How to access the fund
Customers can use either of the announced access channels:
- Open My OneApp and look for the Ziidi Shari’ah investment option.
- Alternatively, dial *334# and follow the available menu instructions.
- Review the product information and terms before opting in.
- Start with the minimum investment of KSh 100 if you decide the fund suits your needs.
- Check the displayed investment balance and daily profit information to monitor performance.
Only use official Safaricom channels. Never share your M-PESA PIN or approve a transaction you did not initiate.
How does the fund generate returns?
This is one of the most important questions to understand before putting money into the product.
A conventional money market fund generally invests in short-term financial instruments, which can include interest-bearing securities and bank deposits. Investors earn returns from the performance of the underlying portfolio, after applicable costs.
A Shariah-compliant fund must follow different rules. It avoids conventional interest-based transactions and invests in activities and structures permitted under Islamic finance principles.
Instead of promising a fixed interest payment, returns arise from the performance of the Shariah-compliant investments held by the fund. The specific sources of income and allocation of assets should be explained in the fund’s official information documents.
The important point is that Shariah-compliant does not mean a fixed return is guaranteed. Investment performance can change, and actual profits may vary over time.
Is the return guaranteed?
Customers should not assume that the fund will pay a particular daily, monthly or annual return.
At launch, Safaricom and GulfCap announced that customers would be able to track daily profit. That feature helps investors monitor performance, but it should not be interpreted as a promise that profits will always be positive or remain at the same level.
Before investing, look for the latest published return information and establish whether the quoted figure is historical, indicative or projected. Also check how the fund calculates and distributes profits.
TechDrivers could not verify a current official annual return figure that should be quoted as the fund’s guaranteed or expected rate. For that reason, this article does not assign the product a percentage return.
What could your investment look like?
The low minimum contribution makes it possible to start small and build an investment habit.
Consider a customer who starts with KSh 100 and adds KSh 10 every day for 30 days.
| Calculation | Amount |
|---|---|
| Initial investment | KSh 100 |
| Daily top-ups | KSh 10 |
| Top-ups over 30 days | KSh 300 |
| Total contributions after 30 days | KSh 400 |
The KSh 400 figure is the total amount contributed, not a forecast of investment value. Any profit or loss would depend on the fund’s performance and applicable costs.
A customer who contributes KSh 500 every month would contribute KSh 6,000 over 12 months, excluding any investment gains or losses.
The lesson is simple: a small starting amount can help build a regular investing habit, but the contribution amount should fit your budget. Do not invest money needed for rent, food, school fees or urgent bills.
What fees should investors expect?
Safaricom and GulfCap have announced free deposits into the fund and free withdrawals to the customer’s M-PESA wallet.
However, free transfers do not necessarily mean that managing the investment has no costs.
Investment funds can incur expenses such as fund management, trustee, custodian and administration fees. These costs may be accounted for within the fund rather than charged as a separate M-PESA transaction fee.
Before investing, check the current terms for:
- Fund management and administration expenses.
- Trustee and custodian charges.
- Any applicable taxes.
- Whether the displayed profit is before or after relevant expenses.
- Any conditions attached to withdrawing or locking funds.
The fund’s official terms and disclosures should take precedence over social media posts or third-party claims about charges.
Can you withdraw your money whenever you want?
GulfCap has announced that customers can withdraw funds into their M-PESA wallets at no cost. The product also includes an option to lock funds to encourage disciplined investing and reduce unplanned withdrawals.
However, investors should not assume every withdrawal scenario is identical. Check the current terms for processing times, any conditions associated with locked funds and how to access money during service interruptions.
A money market fund is an investment product, not the same thing as keeping cash in an ordinary M-PESA wallet. If you need money immediately for emergencies, keep an appropriate amount readily accessible rather than investing every available shilling.
Ziidi Shari’ah vs a conventional money market fund
The main difference is the investment framework, rather than simply the mobile channel used to access the product.
| Feature | Ziidi Shari’ah | Conventional money market fund |
|---|---|---|
| Investment principles | Must comply with Shariah principles | Follows the fund’s conventional investment mandate |
| Interest-based investments | Excluded under its Shariah mandate | May be permitted, depending on the portfolio |
| Returns | Depend on the performance of Shariah-compliant investments | Depend on the performance of the underlying portfolio |
| Guaranteed profits | Should not be assumed | Should not be assumed |
| Risk | Investment risk remains | Investment risk remains |
| Best starting point | Review its Shariah and investment disclosures | Review the fund’s mandate, fees and investment disclosures |
Neither product is automatically better for every investor. The right choice depends on your financial goals, values, liquidity needs, risk tolerance and the actual terms of each fund.
Customers should compare the latest available performance figures on a like-for-like basis rather than choosing a fund based only on its name or advertised daily profit.
What are the risks?
The fund’s Shariah-compliant structure addresses the types of investments it can make. It does not remove the normal risks associated with investing.
1. Investment performance can change
The value and profitability of the underlying portfolio can be affected by financial-market conditions and the performance of its investments. Returns may vary.
2. Fees can affect the final outcome
Even when transfers are free, fund-level expenses can affect the amount investors ultimately earn.
3. Access to funds may depend on the terms
Customers who lock their funds should understand the conditions before doing so. Do not place money needed for an imminent expense into an investment without checking how quickly it can be accessed.
4. Inflation can reduce purchasing power
Even if an investment makes a profit, rising prices can reduce what that money can buy. Investors should assess returns in the context of their financial goals and the cost of living.
5. Digital security remains important
Accessing an investment through a phone makes it important to protect the device, SIM card and M-PESA PIN. Scammers may impersonate customer-care agents or send fake investment messages.
Never share your PIN or one-time passwords with someone claiming to help you register or withdraw money.
What the launch means for Kenya’s digital finance sector
The launch reflects the growing role of mobile platforms in bringing investment products closer to everyday customers.
For years, many Kenyans have primarily used mobile money to receive payments, buy goods, send funds and pay bills. Investment products available through digital channels create another potential use for the same financial infrastructure.
The KSh 100 entry point may make it easier for some customers to begin investing without first accumulating a large amount of money. The option may also broaden access for people who want their investments to follow Shariah principles.
But accessibility is only one part of financial inclusion. Customers also need clear information about investment risks, charges, returns and withdrawal conditions.
For providers, the long-term opportunity depends not only on attracting sign-ups but also on earning customers’ trust through transparent disclosures, reliable service and responsible product design.
For more context on the changing mobile finance landscape, read TechDrivers’ coverage of Kenya’s digital payments and open finance developments involving M-PESA and our analysis of Airtel Money’s London listing and what it means for M-PESA and African fintech.
How to decide whether the fund suits you
Before registering, ask yourself five questions:
- Does the fund’s Shariah-compliant mandate align with my investment preferences?
- Do I understand how the fund generates profit and that returns are not guaranteed?
- Have I reviewed the latest fees, terms and investment disclosures?
- Can I afford to leave this money invested without compromising essential expenses?
- Do I understand how to withdraw funds and protect my M-PESA account?
If you cannot answer these questions confidently, take time to review the official documentation or seek advice from a qualified financial professional.
Frequently asked questions
1. What is the Ziidi Shari’ah Money Market Fund?
It is a Shariah-compliant investment fund launched by Safaricom and GulfCap Investment Bank. It is designed for customers seeking investment opportunities that follow Islamic finance principles.
2. What is the minimum investment?
The announced minimum initial investment is KSh 100. Subsequent top-ups start at KSh 10.
3. How do I access the Ziidi Shari’ah fund?
The announced channels are My OneApp and the USSD code *334#. Follow the official menu instructions and review the terms before registering.
4. How much profit does the fund pay?
Returns depend on the performance of the underlying investments. A current official return figure should be checked through the fund’s official disclosures. Profits should not be treated as guaranteed.
5. Are deposits and withdrawals free?
Safaricom and GulfCap have announced free deposits into the fund and withdrawals to M-PESA. Customers should still review the full terms to understand fund-level expenses, taxes and any applicable conditions.
6. Is Ziidi Shari’ah the same as the conventional Ziidi Money Market Fund?
No. The two funds operate under different investment frameworks. Ziidi Shari’ah follows Shariah principles, while the conventional fund follows its own investment mandate.
7. Is the fund risk-free because it is Shariah-compliant?
No. Shariah compliance describes the investment principles the fund follows. It does not guarantee profits or eliminate investment risk.
8. Is the fund regulated in Kenya?
GulfCap and the Capital Markets Authority have published information about the fund’s regulatory status. Customers can also consult the CMA’s official materials and register of regulated market participants.
Conclusion: Understand the terms before you invest
The Ziidi Shari’ah Money Market Fund gives Kenyan M-PESA customers another way to access formal investments, with an announced starting amount of KSh 100 and subsequent top-ups from KSh 10.
Its Shariah-compliant structure makes it relevant to customers seeking investments aligned with Islamic financial principles, while its mobile access may lower some practical barriers to getting started.
But convenience and a low minimum should not replace careful decision-making. Check the current return information, fees, withdrawal conditions and investment risks before committing money.
The most important rule is to invest based on the product’s documented terms and your financial needs—not on the promise of quick or guaranteed profit.
Editorial note: This article is for general information and education. It is not personal financial or religious advice. Product features and terms may change; consult the fund’s official documentation and a qualified adviser where appropriate.
