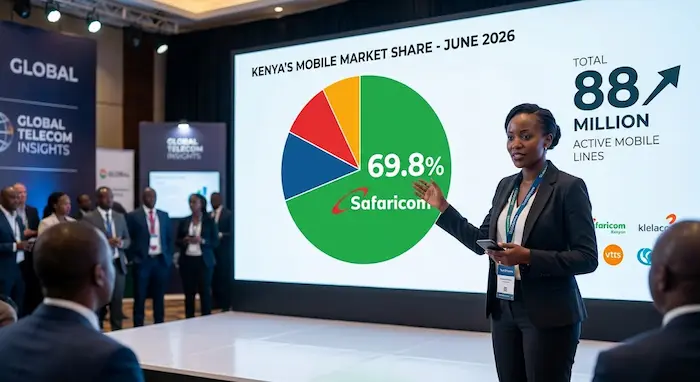

Safaricom strengthened its position in Kenya’s mobile telecommunications market during the 2025/26 financial year, holding 69.8% of active mobile subscriptions by the end of June 2026.
The latest figures from the Communications Authority of Kenya (CA) show that the country’s active mobile subscription base reached almost 88 million connections by June 30, 2026.
Safaricom accounted for about 61.45 million of those subscriptions, followed by Airtel Networks Kenya with approximately 23.60 million.
The figures highlight how concentrated Kenya’s mobile market remains, even as smartphones, mobile broadband and competing digital services continue to expand.
Kenya’s Mobile Market Reaches 88 Million Active Subscriptions
Kenya recorded 87,999,998 active mobile subscriptions at the end of June 2026.
That was an increase from 84,090,298 subscriptions in March 2026, representing growth of about 4.6% in one quarter.
The CA attributes the increase during the financial year partly to customer win-back campaigns conducted by mobile network operators.
Importantly, mobile subscriptions should not be interpreted as the number of individual Kenyans using mobile phones. One person can have multiple SIM cards, while some connections are used for different services and devices.
The CA’s statistics are based on returns from licensed telecommunications service providers.
Safaricom Leads Kenya’s Mobile Market
Safaricom had 61,447,008 active subscriptions at the end of June 2026.
Using the total market of 87,999,998 subscriptions, Safaricom’s market share works out to approximately 69.8%.
That means roughly seven out of every ten active mobile subscriptions recorded by the regulator were on Safaricom’s network.
Airtel Networks Kenya was the second-largest operator with 23,600,969 subscriptions, giving it approximately 26.8% of the market.
The remaining operators accounted for the balance.
Kenya Mobile Market Ranking — June 2026
| Rank | Operator | Active subscriptions | Market share |
|---|---|---|---|
| 1 | Safaricom PLC | 61,447,008 | 69.8% |
| 2 | Airtel Networks Kenya | 23,600,969 | 26.8% |
| 3 | Finserve (Equitel) | 1,468,616 | 1.7% |
| 4 | Jamii Telecommunications | 937,640 | 1.1% |
| 5 | Telkom Kenya | 545,765 | 0.6% |
| Total | Kenya mobile market | 87,999,998 | 100% |
Market shares calculated by TechDrivers from Communications Authority subscription figures. Rounded percentages may not total exactly 100%.
The ranking shows that Safaricom and Airtel together accounted for approximately 96.6% of Kenya’s active mobile subscriptions.
The other three operators collectively represented about 3.4%.
Safaricom’s Market Share Has Increased During the Year
Safaricom’s position did not remain static throughout the 2025/26 financial year.
Its share increased each quarter:
| Quarter | Safaricom market share | Airtel market share |
|---|---|---|
| September 2025 | 65.3% | 30.7% |
| December 2025 | 66.8% | 29.2% |
| March 2026 | 68.9% | 27.6% |
| June 2026 | 69.8% | 26.8% |
Over the nine months from September 2025 to June 2026, Safaricom’s active subscriptions increased from 51.12 million to 61.45 million.
That represents an increase of approximately 10.32 million subscriptions, or about 20.2%.
During the same period, Airtel’s active subscriptions declined from about 24.06 million to 23.60 million.
Telkom Kenya also recorded a significant decline, ending June with 545,765 active subscriptions.
Safaricom Added More Lines Than the Overall Market Growth
One of the more notable features of the CA figures is the relationship between Safaricom’s growth and the overall market.
Kenya’s mobile market added approximately 9.68 million active subscriptions between September 2025 and June 2026.
Safaricom alone added approximately 10.32 million.
This is possible because the overall market figure represents the net change after increases and decreases across all operators.
In other words, Safaricom’s additions were larger than the industry’s overall net growth because some competing operators lost subscriptions during the same period.
The figures do not by themselves explain why individual customers changed operators. The CA, however, linked overall subscription growth during the financial year partly to customer win-back campaigns.
Airtel Remains Kenya’s Second-Largest Mobile Operator
Despite losing some market share during the 2025/26 financial year, Airtel remains the clear second-largest mobile operator in Kenya.
Airtel had 23.60 million active subscriptions in June, equivalent to approximately 26.8% of the market.
The gap between Safaricom and Airtel was therefore about 37.85 million subscriptions.
The two operators are also competing beyond traditional voice and SMS services, particularly in mobile data and mobile money.
For consumers, competition between the two large networks can influence pricing, promotions, network investment and the availability of different services.
Safaricom Also Leads Mobile Broadband
The Safaricom lead extends beyond overall mobile subscriptions.
According to the latest CA figures, Safaricom held approximately 64.4% of Kenya’s mobile broadband subscriptions at the end of June 2026.
Kenya had approximately 54.9 million mobile broadband subscriptions, meaning broadband connectivity is becoming an increasingly important part of the mobile market.
This is particularly relevant as smartphone adoption continues to increase.
TechDrivers recently reported on the rise of smartphones in Kenya, with 52.26 million smartphones connected to mobile networks by June 2026.
Read: Kenya Now Has 52.26 Million Smartphones — What the Latest CA Data Means
The growth of smartphones and mobile broadband means competition between operators is no longer only about calls and SMS.
Network coverage, 4G and 5G availability, data prices, network reliability and customer experience have become increasingly important.
M-Pesa Gives Safaricom an Even Larger Position in Mobile Money
Safaricom’s strongest market concentration is in mobile money.
The CA reported that Safaricom held 88.8% of mobile money transfer subscriptions at the end of June 2026.
That was slightly lower than its earlier share, while Airtel Money increased its position.
This distinction is important because Safaricom’s 69.8% mobile subscription share and its 88.8% mobile money share measure different markets.
A customer can therefore be part of Safaricom’s mobile subscription base while using other services from competing operators.
Read: Kenya Mobile Money Subscriptions Hit 54 Million as M-Pesa Holds 88.8% Share
Kenya’s Mobile Market Is Becoming More Smartphone-Driven
The mobile subscription figures become more interesting when viewed alongside Kenya’s changing device market.
By June 2026, smartphone connections had reached 52.26 million, while feature-phone connections stood at about 27.42 million.
That means smartphones represented approximately 65.6% of connected mobile devices.
The shift matters because smartphones provide access to services that go far beyond conventional calls and text messages.
These include:
- Mobile banking
- Mobile money applications
- E-commerce
- Social media
- Streaming
- Online education
- Artificial intelligence tools
- Business applications
- Digital advertising
- Cloud services
For telecom operators, the growth of smartphones also means increasing demand for mobile broadband capacity.
For Kenyan businesses, it means that mobile-friendly websites, social media and digital customer-service channels are becoming increasingly important.
What the Numbers Mean for Kenyan Consumers
For consumers, the changing market creates several practical considerations.
Network coverage remains important
A large subscriber base does not automatically mean every customer receives the same network experience everywhere.
Coverage can vary by location, technology and network capacity.
Customers should therefore consider actual network performance in the areas where they live, work and travel.
Data pricing matters more
As smartphones become more common, consumers are using mobile networks for video, social media, work, banking and other data-intensive services.
This makes the cost and size of data bundles increasingly important when choosing a network.
Competition still matters
Although Safaricom has the largest market share, Airtel and smaller operators remain part of Kenya’s telecommunications ecosystem.
Competition can give consumers alternative pricing, packages and services.
The market-share figures should therefore be viewed as a snapshot of subscriptions, rather than a direct measure of every aspect of customer experience.
What the Numbers Mean for Kenyan Businesses
The mobile market is also important for businesses.
A company targeting Kenyan consumers can no longer treat mobile connectivity as a secondary channel.
Businesses should consider:
- Mobile-friendly websites
- WhatsApp and other digital communication channels
- Mobile payment options
- Social-media marketing
- Short-form video
- Mobile applications where appropriate
- Fast-loading websites for mobile users
- Cybersecurity and customer-data protection
The growth in smartphones and mobile broadband expands the potential audience for digital services.
At the same time, businesses need to recognise that connectivity does not automatically translate into customer engagement. Content, pricing, trust, convenience and service quality still influence whether customers use a digital product.
The Mobile Market Is Bigger Than Safaricom and Airtel
While Safaricom and Airtel dominate the headline numbers, Kenya’s mobile ecosystem includes several other licensed operators.
Finserve, Jamii Telecommunications and Telkom Kenya together accounted for roughly 3.4% of active mobile subscriptions in June 2026.
Their smaller shares do not mean they are irrelevant to the wider communications market.
Different operators can target different customer segments and services, while some companies also participate in specific connectivity or digital-service markets.
The broader telecommunications sector therefore includes mobile voice, mobile broadband, fixed internet, mobile money, machine-to-machine connectivity and other digital services.
What Happens Next?
The next phase of competition in Kenya’s mobile industry is likely to be increasingly shaped by data rather than simply the number of SIM cards.
Smartphone adoption is increasing, mobile broadband is expanding and consumers are using more online services.
At the same time, operators have to invest in network capacity and compete on pricing and customer experience.
For Safaricom, the latest figures demonstrate the scale of its existing mobile customer base.
For Airtel and smaller operators, the numbers illustrate the size of the gap they face in the mobile subscription market.
For consumers, the important question is not simply which operator has the largest number of connections. It is how network investment, pricing, coverage, data services and competition translate into better services.
Frequently Asked Questions
What is Safaricom’s market share in Kenya?
Safaricom held 69.8% of Kenya’s active mobile subscriptions at the end of June 2026, according to Communications Authority of Kenya data.
How many Safaricom subscribers are there in Kenya?
Safaricom had approximately 61.45 million active mobile subscriptions at the end of June 2026.
How many mobile subscriptions does Kenya have?
Kenya had 87,999,998 active mobile subscriptions at the end of June 2026.
What is Airtel Kenya’s market share?
Airtel Networks Kenya had approximately 23.60 million active subscriptions, representing about 26.8% of the total market.
Does 88 million mobile subscriptions mean Kenya has 88 million mobile users?
No. Mobile subscriptions are not equivalent to individual people. One person can have multiple SIM cards or connections, so subscription figures should not be interpreted as a count of unique users.
What is Safaricom’s mobile broadband market share?
Safaricom held approximately 64.4% of Kenya’s mobile broadband subscriptions at the end of June 2026.
What is Safaricom’s mobile money market share?
Safaricom held 88.8% of mobile money transfer subscriptions at the end of June 2026.
Why is Safaricom’s market share so important?
Safaricom’s share provides an indication of the company’s position within Kenya’s mobile subscription market. However, subscriber share is only one measure of competition and does not capture every aspect of network quality, pricing, usage or customer experience.
Editorial Note
This article is based primarily on the Communications Authority of Kenya’s Sector Statistics Report for Q4 of the 2025/26 financial year, covering the quarter ended June 30, 2026.
The CA states that its quarterly sector statistics are compiled from returns submitted by licensed service providers and may be subject to revision. Active subscriptions refer to connections that meet the regulator’s activity criteria and should not be treated as a direct count of unique individuals.
Market-share percentages in this article were calculated by TechDrivers using the operator subscription figures and the total market reported by the CA.
Conclusion
Safaricom ended Kenya’s 2025/26 financial year with 69.8% of the country’s active mobile subscriptions, reinforcing its position as the largest mobile operator.
But the bigger story is the transformation happening around that market share.
Kenya now has almost 88 million active mobile subscriptions, more than 52 million smartphones, and nearly 55 million mobile broadband subscriptions.
The numbers show a market moving increasingly toward smartphone-led, data-driven connectivity while traditional voice and SMS services remain significant.
For consumers and businesses, the next stage of Kenya’s telecom competition will increasingly be about data, network quality, pricing, digital services and customer experience—not simply the number of SIM cards on each network.
